
PMJJBY, PMSBY and Atal Pension Yojana
PMJJBY, PMSBY and Atal Pension Yojana. A detailed chapter in Financial Inclusion & Government Financial Schemes, with explanations and examples for Indian banking examinations.
By Akhilesh Saini · Reviewed 7 Oct 2026
1. Why social security is part of financial inclusion
A bank account helps manage today's money.
But families also face:
- death;
- accident;
- disability;
- old age.
Financial inclusion is incomplete without risk protection.
Three flagship schemes are:
- PMJJBY
- PMSBY
- APY
2. Jan Suraksha architecture
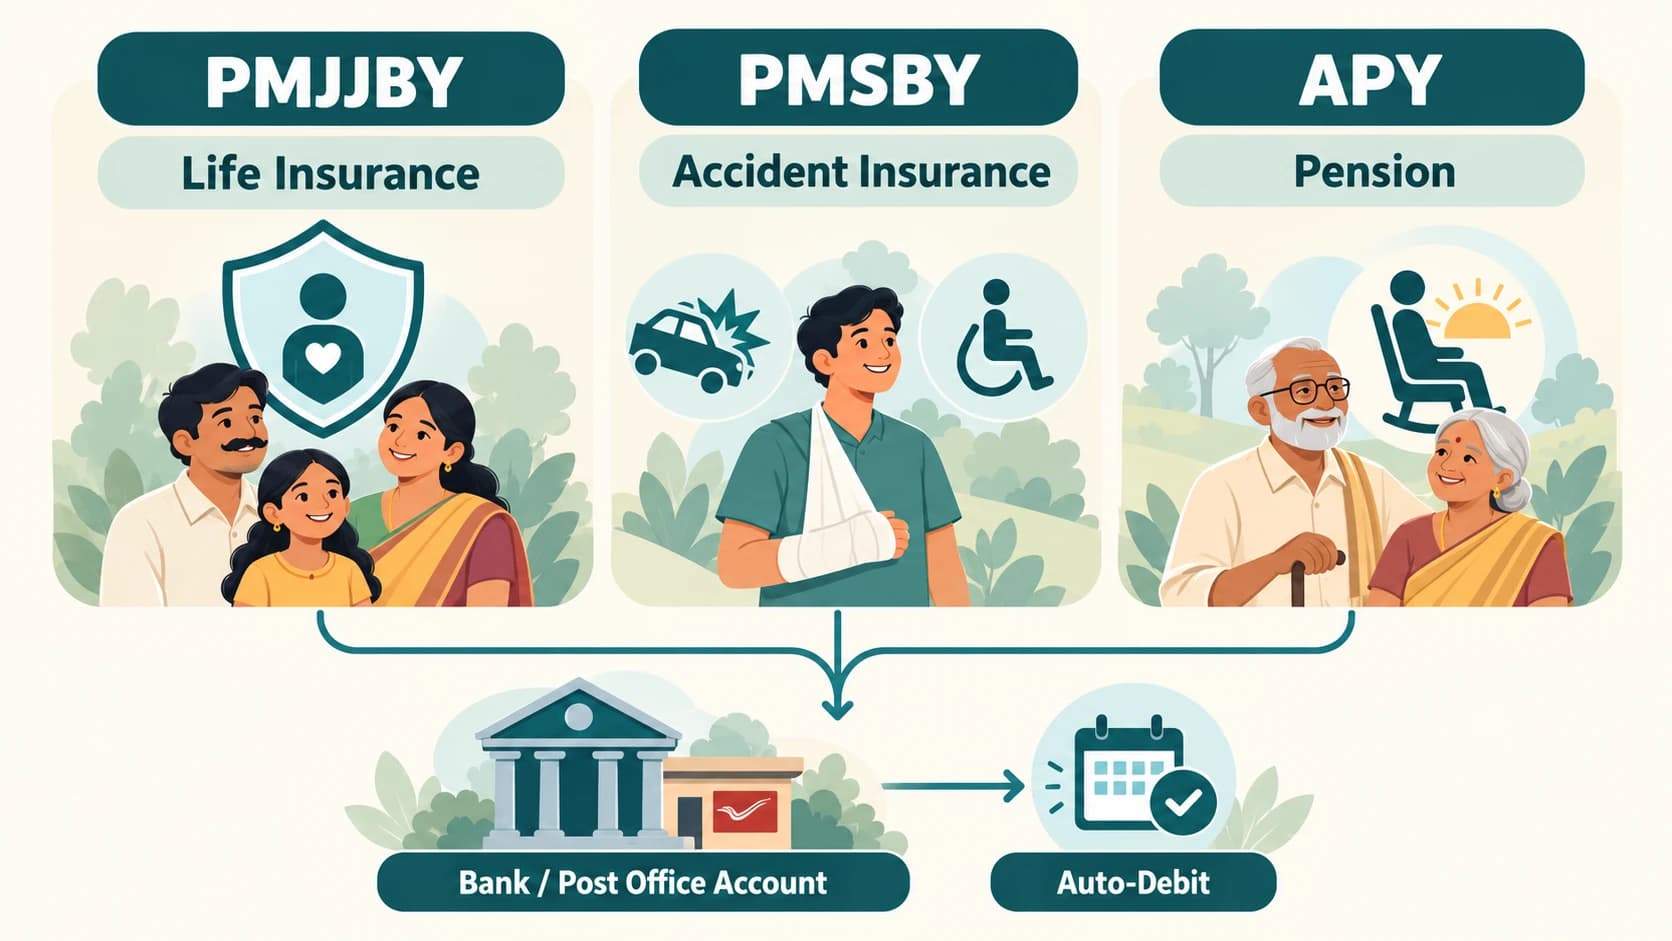
PMJJBY and PMSBY are low-cost insurance schemes linked to bank/post-office accounts.
APY is a pension scheme.
They use the account as an infrastructure for:
- auto-debit;
- enrolment;
- recurring contribution/premium;
- benefit delivery.
3. PMJJBY
PMJJBY stands for:
Pradhan Mantri Jeevan Jyoti Bima Yojana
It is a renewable one-year term life insurance scheme.
4. What PMJJBY covers
PMJJBY pays the insured benefit on:
death due to any cause,
subject to scheme rules.
This is broader than accidental-death-only insurance.
5. PMJJBY is pure term insurance
There is no:
- maturity value;
- investment corpus;
- surrender value like savings-type life insurance.
The purpose is:
low-cost mortality protection.
6. Entry age and continuation
The scheme has:
- a joining age range;
- an upper age at which coverage terminates subject to annual renewal.
The enduring exam concept is:
entry age and maximum continuation age are different.
7. Auto-debit
Premium is paid through:
- bank account; or
- post-office account
using auto-debit after subscriber consent.
This reduces manual renewal friction.
8. Lien period
For first-time enrolment/re-enrolment, the current PMJJBY framework contains a waiting/lien rule for non-accidental death.
This should be checked from the latest scheme FAQ because it can be operationally important.
9. PMSBY
PMSBY stands for:
Pradhan Mantri Suraksha Bima Yojana
It is a renewable one-year personal accident insurance scheme.
10. What PMSBY covers
It covers specified consequences of accident such as:
- accidental death;
- permanent total disability;
- specified partial disability.
It does not provide the same "death due to any cause" protection as PMJJBY.
11. PMJJBY vs PMSBY
| Feature | PMJJBY | PMSBY |
|---|---|---|
| Type | Life insurance | Personal accident insurance |
| Death cover | Death due to any cause | Accidental death |
| Disability | Not the main cover | Yes, specified accidental disability |
| Renewal | Annual | Annual |
| Premium debit | Bank/Post office | Bank/Post office |
12. Can a person have both?
Yes, if eligible.
The schemes cover different risks.
Example:
- PMJJBY protects life risk broadly;
- PMSBY protects accident death/disability.
They complement one another.
13. Multiple bank accounts do not multiply scheme cover
A person may have multiple bank accounts.
But scheme membership is restricted according to rules so that the person cannot claim multiple covers merely by enrolling through multiple accounts.
This is a common exam trap.
14. Atal Pension Yojana - APY
APY is a Government-backed pension scheme administered under PFRDA's pension architecture.
It was introduced with effect from 1 June 2015.
Its objective is old-age income security, especially for lower-income and unorganised-sector workers.
15. APY is not insurance
APY is a pension scheme.
PMJJBY/PMSBY are insurance schemes.
The distinction:
- insurance protects against risk event;
- pension provides income after retirement age according to the scheme structure.
16. APY entry age
A person can join within the prescribed age range.
Why a maximum joining age?
Because contributions need enough years to build the pension entitlement before age 60.
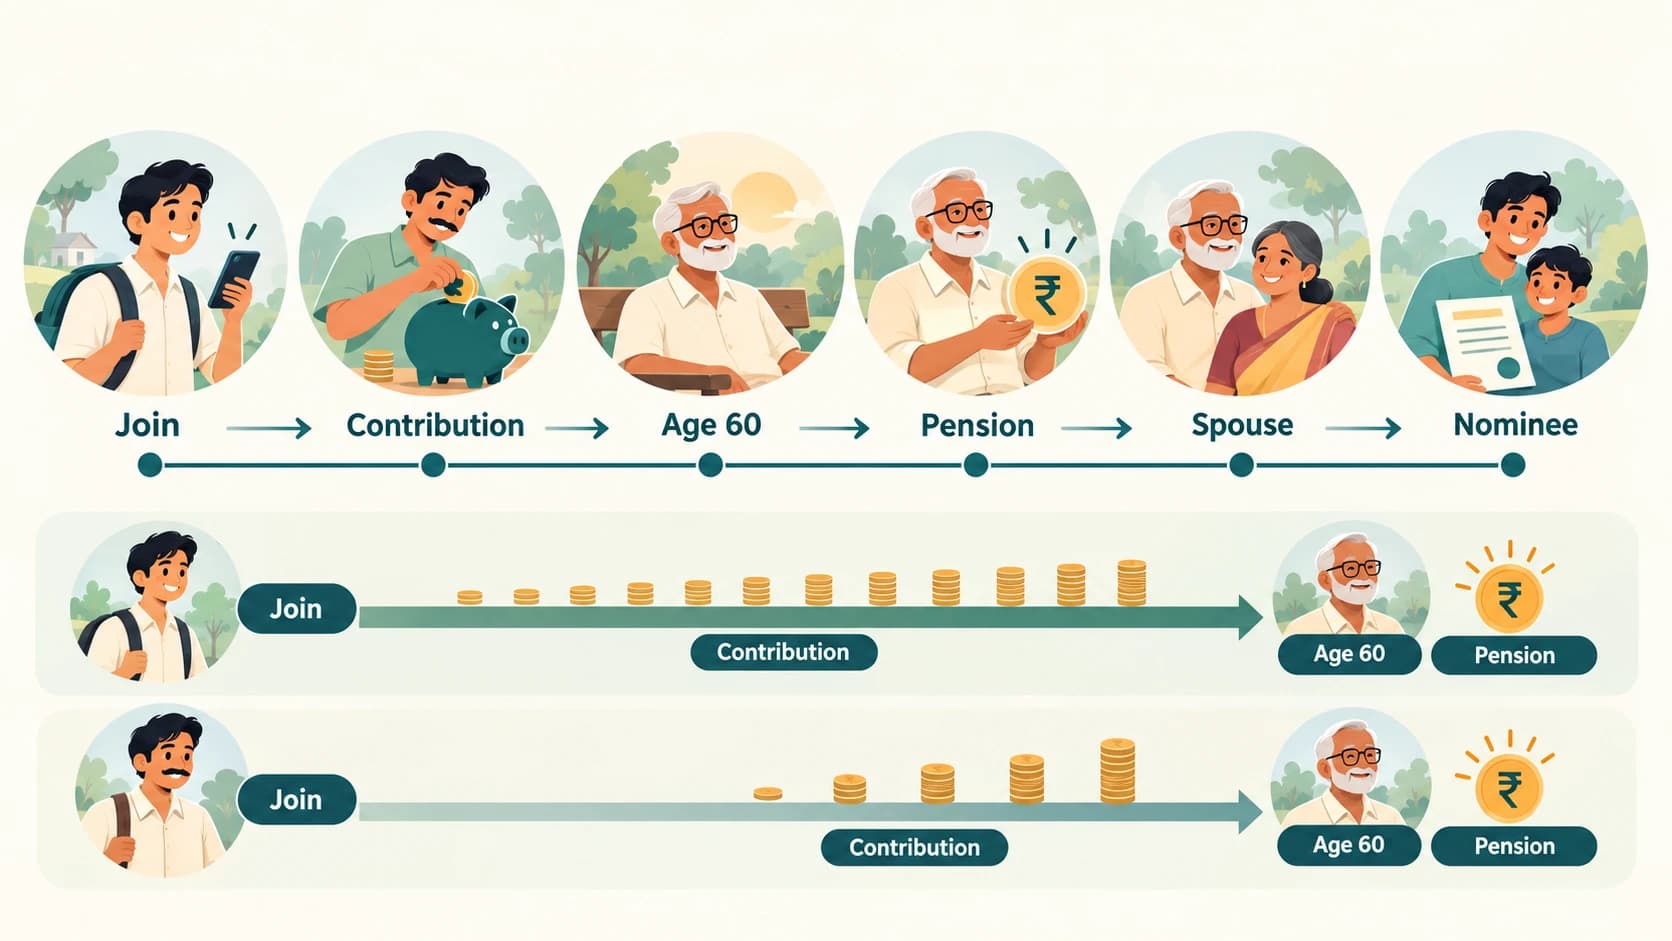
17. Pension starts after 60
APY provides a minimum guaranteed monthly pension after age 60 based on the selected pension slab and regular contributions.
Current slabs are updateable scheme parameters.
18. Contribution depends on entry age
A younger entrant contributes for more years.
Therefore:
lower monthly contribution can accumulate over a longer period.
An older entrant must contribute more per period for the same pension slab.
19. Spouse benefit
After the subscriber's death, the spouse can receive the pension under the APY structure.
After both subscriber and spouse die, the eligible nominee receives the accumulated indicative corpus according to the scheme.
20. Income-tax payer restriction
Since the rule effective from 1 October 2022:
a person who is or has been an income-tax payer, as defined in the APY eligibility rule at the date of application, cannot open a new APY account.
Existing subscribers who joined before the cut-off can continue according to PFRDA rules.
21. APY and bank/post-office account
An APY subscriber needs an eligible savings bank/post-office savings account for:
- enrolment;
- auto-debit of contributions.
This shows again how basic account access enables social security.
22. APY vs NPS
APY and NPS are both pension-system products, but:
APY
- Government-backed minimum guaranteed pension slabs;
- targeted heavily toward unorganised/low-income workers;
- prescribed contribution linked to age/pension slab.
NPS
- market-linked defined-contribution pension architecture;
- accumulated corpus depends on contributions and investment performance.
Do not confuse the two.
23. Premium vs contribution
Insurance premium
Pays for risk cover during a period.
If the insured event does not occur, pure-risk insurance usually has no maturity value.
Pension contribution
Builds entitlement/corpus under a retirement scheme.
This distinction helps remember PMJJBY/PMSBY vs APY.
24. Why banks matter in these schemes
Banks/Post Offices provide the account and transaction infrastructure for:
- enrolment;
- debit;
- renewal;
- customer service;
- beneficiary linkage.
The insurer/PFRDA architecture provides the actual insurance/pension product.
Quick check - BA-09-04
- Is PMJJBY life insurance or accident insurance?
- Does PMSBY cover death due to any cause?
- Can one person multiply PMJJBY cover using several bank accounts?
- Is APY an insurance scheme?
- At what age does APY pension normally begin?
- Can a new income-tax payer join APY under the current eligibility rule?
Quick answers
- Life insurance.
- No; it is accident insurance.
- No.
- No; it is a pension scheme.
- 60 years.
- No, under the current rule.