
NPAs, Stressed Assets & Recovery
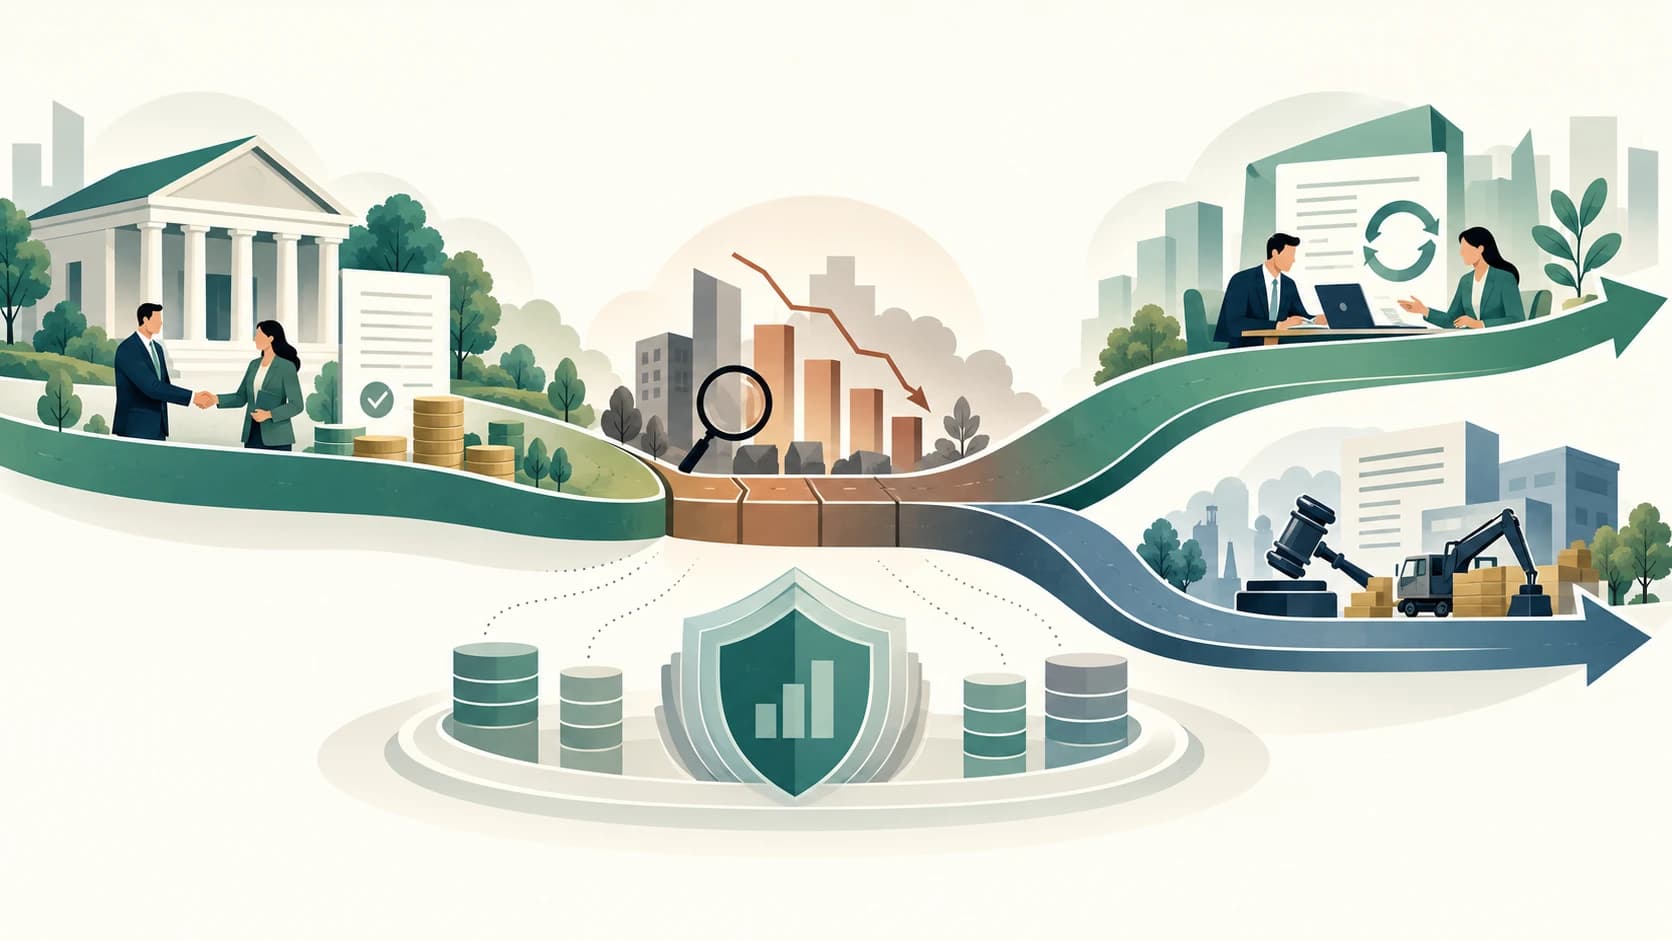
Lending creates income for banks, but it also creates credit risk. When borrowers begin missing payments, banks must identify stress early, stop recognising unrealised income, classify deteriorating assets correctly, create provisions, attempt resolution and—where necessary—use legal recovery mechanisms. This module explains that full journey from a performing loan to SMA, NPA, restructuring, write-off, recovery and resolution.
Recommended prerequisite: Module 06 - Lending, Credit & Interest Rates.
Purpose of this module: Lending creates income for banks, but it also creates credit risk. When borrowers begin missing payments, banks must identify stress early, stop recognising unrealised income, classify deteriorating assets correctly, create provisions, attempt resolution and—where necessary—use legal recovery mechanisms. This module explains that full journey from a performing loan to SMA, NPA, restructuring, write-off, recovery and resolution.
What you will learn
By the end of Module 07, you should be able to:
- explain what an NPA is and why the 90-day rule matters;
- distinguish overdue, out-of-order, SMA and NPA status;
- explain special NPA rules for CC/OD, bills and agricultural advances;
- distinguish standard, sub-standard, doubtful and loss assets;
- explain why income recognition changes once an account becomes NPA;
- understand the logic of provisioning and the major provisioning categories;
- distinguish Gross NPA from Net NPA;
- explain SMA-0, SMA-1 and SMA-2;
- explain why stressed-asset resolution should begin before an account becomes NPA;
- explain restructuring and resolution plans under RBI's Prudential Framework;
- distinguish restructuring, compromise settlement, technical write-off and waiver;
- explain what a wilful defaulter is and why wilful default is different from ordinary default;
- distinguish recovery from resolution;
- explain the purpose of SARFAESI, DRTs and the IBC;
- describe the broad SARFAESI recovery sequence;
- explain how DRTs and DRAT fit into bank-debt recovery;
- explain the basic Corporate Insolvency Resolution Process under IBC;
- explain the role of Asset Reconstruction Companies;
- understand how stressed loans can be transferred/sold; and
- recognise which recovery rules and thresholds must be kept current.
Chapters
Non-Performing Assets: Meaning and Recognition
Non-Performing Assets: Meaning and Recognition. A detailed chapter in NPAs, Stressed Assets & Recovery, with explanations and examples for Indian banking examinations.
Asset Classification, Provisioning and Special Mention Accounts
Asset Classification, Provisioning and Special Mention Accounts. A detailed chapter in NPAs, Stressed Assets & Recovery, with explanations and examples for Indian banking examinations.
Stressed Assets, Restructuring, Write-Offs and Wilful Default
Stressed Assets, Restructuring, Write-Offs and Wilful Default. A detailed chapter in NPAs, Stressed Assets & Recovery, with explanations and examples for Indian banking examinations.
Loan Recovery: SARFAESI, DRTs, IBC and Asset Reconstruction Companies
Loan Recovery: SARFAESI, DRTs, IBC and Asset Reconstruction Companies. A detailed chapter in NPAs, Stressed Assets & Recovery, with explanations and examples for Indian banking examinations.